
Native vs Liquid Staking on Solana
Native staking keeps SOL in a stake account your wallet controls. Liquid staking swaps it for a token, an LST, that you can trade or use in DeFi while it keeps earning. Both delegate to validators and earn the same base reward. What separates them is the pool's cut of that reward, 4 to 7% among the pools below, and what it costs to get back out.
What native staking is
Native staking means you delegate SOL directly to a validator from your own wallet. The SOL sits in a stake account only you control, rewards land and compound automatically at the end of every epoch, and no pool sits between you and the stake program. To get the SOL back you unstake and wait out the rest of the current epoch: 13 hours on average, 26 at the outside. New to it? Start with how to stake Solana.
Liquid staking and LSTs
Liquid staking routes your SOL through a stake pool. In return you receive a liquid staking token (LST), a standard SPL token that represents your share of the pool. The LST does not pay rewards directly. Its exchange rate against SOL drifts upward each epoch as the pool earns, so your yield shows up as the token becoming worth more SOL over time.
Because an LST is an ordinary token, you can hold it, swap it to SOL instantly, or put it to work as collateral and liquidity across Solana DeFi while it keeps earning. It remains the minority route, and a shrinking one: liquid staking holds 12.5% of all staked SOL, down from a peak of 15.7% in January 2026, and lower in each of the 8 months since.
You do not have to sell your stake to get in. The stake-pool program accepts an existing stake account directly and issues pool tokens against it, so a native position can become an LST with no deactivation and no wait, provided it is delegated to a validator the pool already stakes to. The reverse instruction hands you back a stake account rather than SOL, which then follows the ordinary native timetable.
Native vs liquid: side by side
| Native staking | Liquid staking (LST) | |
|---|---|---|
| Custody | Your stake account, non-custodial | Pool contract holds the stake; you hold the token |
| Liquidity | Locked until deactivation completes | Tradable instantly on DeFi markets |
| Exit speed | Rest of the epoch, 26 hours at most | Seconds through a DEX swap or the pool's reserve; otherwise the rest of the epoch |
| Exit cost | None when you wait; a fee to sell the stake account at once | The pool's withdrawal fee, or the market discount on a swap |
| Usable in DeFi | No | Yes (lending collateral, LPs, looping) |
| Rewards | Auto-compounded into the stake account | Accrue as the token's value rises |
| Validator choice | You pick the validator | Pool decides, though some let you direct it |
| Taxes (typical) | Per-epoch rewards often taxed as income | Often deferred until you sell or redeem |
| Extra risk | Validator performance only | Validator + smart contract + possible discount on exit |
The main Solana LSTs
If you go liquid, the token you hold matters. The leading LSTs differ in who issues them, how large and therefore how tradable they are, and whether you get any say in the validator behind them.
| LST | Issuer | SOL held | What sets it apart |
|---|---|---|---|
| bnSOL | Binance | 10.80M | Issued by the exchange: the SOL behind it is held by Binance, not by a pool on chain |
| JitoSOL | Jito | 10.37M | Its stake is assigned by Jito's Steward program, which scores validators each cycle |
| jupSOL | Jupiter | 5.17M | Built into the Jupiter app |
| mSOL | Marinade | 2.26M | The original Solana LST, launched in 2021, on Marinade's own program rather than the SPL pool |
| INF | Sanctum | 1.79M | An index across other LSTs rather than a single pool |
| pSOL | Phantom | 1.62M | Phantom's own token, staked from inside the wallet |
Seven-day averages from the daily series behind our liquid staking dashboard; the order is read from it rather than fixed.
An exchange-issued token is not liquid staking in the sense the rest of this page uses it: the SOL behind it is a claim on the exchange, so the custody argument for staking yourself does not survive the wrapper. Among tokens backed by a pool on chain, JitoSOL is the largest, and size is what makes a token widely accepted as DeFi collateral and cheap to leave. Two smaller pools, JPool and The Vault, are worth knowing for a different reason: they let you choose the validator behind your LST, Stake.Cake included.
Yield: what each actually earns
The base reward is identical for both routes, because both ultimately delegate to validators. Solana inflation pays staked SOL about 4.9% APY before commission, distributed each epoch in proportion to your stake. On top of that, MEV changes the picture:
- Native staking earns inflation plus whatever MEV your validator passes through. The pass-through is the operator's choice, so it varies from nothing to everything.
- Every major LST captures MEV, mSOL included: they delegate to validators in Jito's tip auction, and the tips reach the token through its stake accounts each epoch.
- What actually differs is the pool's own fee, taken off the rewards before they reach the token, and which validators the pool delegates to.
Those are the mechanics. Here is what they came to over the last completed epoch:
| Route | Validators earned | Pool fee | You keep |
|---|---|---|---|
| Native — median validator baseline | 4.91% | — | 4.91% |
| JitoSOL Jito | 4.89% | 4.0% | 4.69% |
| vSOL The Vault | 4.86% | 5.0% | 4.62% |
| bSOL BlazeStake | 4.68% | 5.0% | 4.45% |
| JSOL JPool | 4.66% | 7.0% | 4.33% |
| JupSOL Jupiter | 4.54% | 5.0% | 4.31% |
| jagSOL JagPool | 4.53% | 5.0% | 4.30% |
| Stake.Cake our validator | 4.20% | — | 4.20% |
| mSOL Marinade | 5.00% | — | — |
“Validators earned” is the yield each pool's validators actually produced. The pool fee is that pool's cut of the rewards, read live from its on-chain stake pool account. “You keep” is what is left for the token holder. Native rows carry no pool layer, so the two columns match; a validator's own commission is already reflected in what it earned. A dash means no fee could be read from the pool's own account, so no net figure is claimed — Marinade's pool is not an SPL stake pool, so it always sits there and its row shows gross only.
The routes sit closer together than their headline APYs suggest. Every pool above delegates to the same kind of validator, so what those validators earned spans just 0.47 percentage points. What separates the last column is the pool's own fee, running from 4.0% to 7.0% of your rewards. Best to worst among the liquid routes is 0.39 points, or 3.9 SOL a year on a 1,000 SOL position.
One number to disregard wherever you see it quoted: the network-wide average. Across all stake it sits at 3.70%, against the median validator's 4.91% — and no delegator receives it. 60 validators charge 100% commission and hold 24.1% of all staked SOL: exchanges and operators staking their own SOL, who keep the rewards because there is nobody else to pay. That stake is in every network average and in nobody's wallet. The median is the number to compare a route against, and the spread worth acting on is the one in the table above — wider than the gap between native and liquid.
These are what each route produced over a past epoch, not a promise about the next one: a validator's commission and reliability decide how much of the yield reaches you, and both can change after you delegate. The staking calculator turns a rate into SOL for your own position.
What leaving early costs
Native staking's own way out is to unstake, wait for the epoch to end and withdraw, with no fee. A stake account can also be sold at once, through Sanctum or a wallet's instant unstake, for a fee, and how to unstake Solana compares both.
An LST has two ways out, and both cost something. Redeeming through the pool returns SOL at the token's on-chain value, less a withdrawal fee. Jito's pool, like other SPL pools, pays at once from its reserve while that holds enough SOL, and otherwise hands back a stake account that you unstake like a native one. Marinade pays out after the epoch ends. Swapping on a DEX settles in seconds at the market price, which can sit below the on-chain value.
| Token | Redeem through the pool | Swap 100 SOL | Swap 10,000 SOL |
|---|---|---|---|
| JitoSOL | 0.10% | 0.08% 5.9 days of yield | 0.10% 7.3 days of yield |
| mSOL | 0.20% | 0.10% 7.3 days of yield | 0.19% 13.9 days of yield |
The pool's own fee for redeeming, and how far below the token's on-chain value a swap of that size lands right now, also shown as days of the network's yield. Values and fees read from each pool's account on chain; quotes from Jupiter.
At today's market depth a 100 SOL swap costs less than the pool's own withdrawal fee for both tokens, so the instant way out is also the cheaper one at that size. The discount grows with the size of the position and shrinks with the depth of the token's market. Aggregators such as Sanctum also swap one LST directly for another, which avoids paying an exit twice.
Using your LST in DeFi
The reason to accept the extra risk of an LST is capital efficiency: the same SOL earns staking yield and stays productive elsewhere. Common uses:
- Collateral for borrowing on lending markets like Kamino, MarginFi and Save, so you can borrow against staked SOL without unstaking.
- Liquidity provision in LST/SOL pools to earn trading fees on top of staking yield.
- Looping (borrow, restake, repeat) to amplify yield, which also amplifies risk; treat it as advanced, not a starting move.
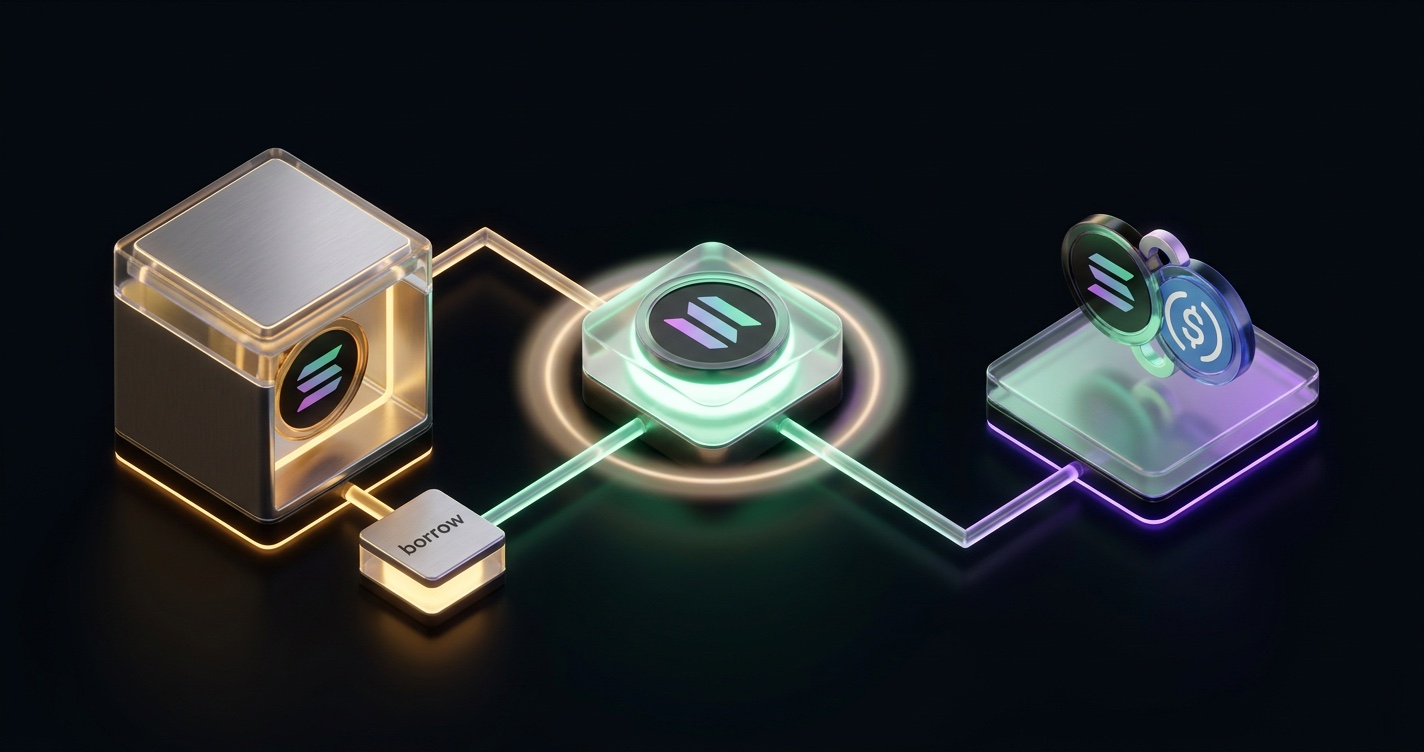
Native stake cannot do any of this. If your SOL is just sitting and compounding, that simplicity is a feature, not a limitation.
Taxes: a quick note
The two routes can be taxed differently. Native rewards arrive as new SOL each epoch, which many jurisdictions treat as income on receipt. Most LSTs accrue value through a rising exchange rate rather than new tokens, which can defer recognition until you sell or redeem, similar to an appreciating asset. This is a genuine difference, not tax advice; rules vary by country and change, so confirm with a professional for your situation.
Risks to understand
- Smart-contract risk (liquid only). An LST depends on the pool's program. Most on-chain pools run the widely deployed, audited SPL stake-pool program; Marinade runs its own. Withdrawal is an instruction on that program, not a feature of a website, so a pool whose front end disappears is still redeemable by anything that can send the transaction.
- The discount on exit (liquid only). An LST's on-chain value rises each epoch, but its market price can sit below it, which is what the table above measures, and the gap widens when many holders want out at once. Redeeming through the pool avoids the discount for the pool's fee, so a deep discount hurts only if you must sell at once: in a panic, or when the token is posted as collateral and the discount triggers a liquidation.
- Leverage risk (liquid only). Looping and lending stack extra layers; each added protocol is one more thing that can break. Keep early positions simple.
- Validator performance (both). A validator with downtime or a high skip rate produces fewer rewards to share. This is why choosing a good validator matters in either model.
- Slashing. Solana does not currently slash stake for ordinary downtime, so the practical downside is reduced rewards rather than loss of principal.
Which should you choose?
Choose native if you hold SOL for the medium to long term, want the simplest non-custodial setup, and value automatic compounding with no pool fee and nothing to pay on the way out.
Choose liquid if you want your staked SOL to stay productive, as DeFi collateral or liquidity, or if you might need to exit in seconds rather than wait out an epoch. Which token depends on what you will do with it and how much of it you may need to sell at once.
You can do both. A common split is a core native position for the long haul plus a smaller liquid position for DeFi. Either route can delegate to Stake.Cake, natively or through JPool or The Vault.
Stake your way
Delegate natively for full control, or pick a liquid staking pool that routes to Stake.Cake and keep your SOL liquid while it earns.